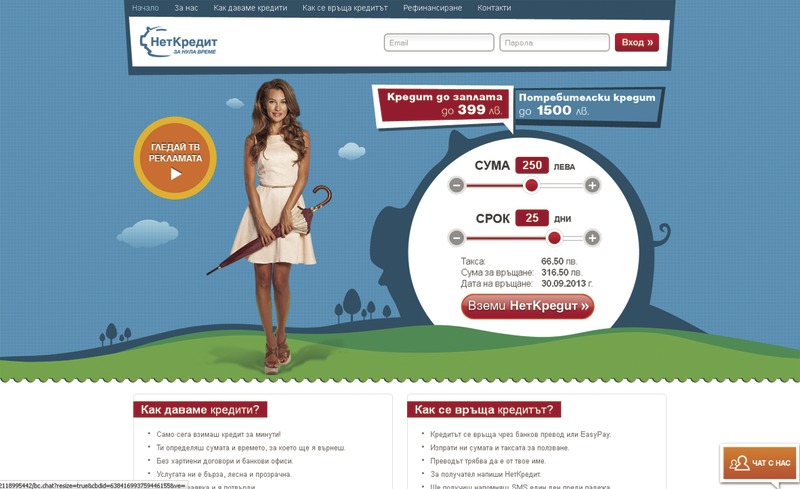
You need money urgently? Take a quick loan now! Such advertising messages have been aired on television for two months. Companies for fast loans, as if to fill in the weakened flow from the banks, promise to citizens miracles – no interest, no collateral, and an approval of the application within a few minutes. It is just too much tempting. And If people have an urgent need of, say, 500 levs, they would not even think about other options. Only to realize later that the decision to take 600 levs in such loans means paying a minimum of 60 levs in interest every month, which for a year amounts to at least 720 levs. The principal is a separate thing to repay. Those who were taken in by such ads are already thousands. Therefore it is not surprising that against the scheme are to be read many comments on the Internet. Most of which can be summed up with in one question: Where is the Central Bank in this situation?. We also asked the Bulgarian National Bank ( BNB ) to comment. From there the BANKER received an extensive response. We encourage everyone to read it in order to know in which issues one can seek his rights before the National Bank and when – before other state institutions.
Among the financial institutions under the Law on Credit Institutions fall also those whose main activity is lending funds not raised through public deposits and other repayable funds. They are not subject to licensing or registration under another law, so under Article 3, paragraph 2 of the same act they are registered with the Bulgarian National Bank. The basic requirements which must be met by them to get registered, are defined in the law, and documents such as Ordinance No 26 of the National Bank for financial institutions. In a brief summary, these are requirements to own and maintain certain levels of equity capital, compliance with the criteria for qualifications, experience and reputation of the persons managing and representing the financial institution and its shareholders with qualifying holdings (10 or more percent of the capital) .
Financial institutions that provide loans or perform financial leasing are required to register with the Central Credit Register and submit monthly information required under the the procedure laid down in Regulation No 22 of the Central Bank (BNB). All financial institutions registered with the BNB periodically provide information about their financial situation, through which it monitors their compliance with the minimum capital requirement, the violation of which could threaten the interests of their creditors. Ordinance No 26 of the BNB provides basic requirements for financial institutions under which they should have rules for the work they perform, while the lending entities must also have statutes for the terms and conditions under which they provide sums to customers and establish relationships with them.
The C-Bank exerts control over the registered financial institutions and their compliance with exactly the above requirements, which essentially doesn’t cover the way in which they carry out their activities, the amount of interest on the loans they grant, or annual percentage rate, nor the means by which they collect their money back, etc. That is why the
powers of the Central Bank to sanction
a registered financial institution are limited solely to a violation of these requirements which the Central Bank controls and an ultimate measure is the removal of the financial institution from the register, which deprives it of the right to perform such basic operations. Deletion can be done at the request of the financial institution itself. Since the entry into force of Regulation No 26 (15 May 2009) until August 1, 2013 a total of 38 financial institutions have been deleted from the register.
The fact that the Bank has no control over the economic activity of financial institutions does not mean that this activity is not legally regulated and there is no one to control it. For example, in establishing relationships with customers, financial institutions in their capacity of entities liable under the Law on Measures against Money Laundering implement measures for customer due diligence. Control under this Act shall be exercised by the Minister of Finance and Chairman of the National Security State Agency.
In cases where financial institutions provide services remotely or exercise the granting of consumer credits, the provisions of the Act for the Provision of Financial Services at a Distance apply and respectively the Consumer Credit Act. Under those Acts
the control functions are carried out
by the Commission for Consumer Protection (CCP) to the Minister of Economy, Energy and Tourism. CCP monitors and investigates these financial institutions and the terms of consumer credit agreements and investigates whether consumers are informed of the terms of their products with the provision of the Single European form. The Commission is the institution that has the right to impose sanctions on financial institutions on compliance with these and other requirements under the respective law. In the past year, the CCP checked the general conditions of some of the financial institutions. As a result of inspections by the CCP, these financial institutions have changed their general conditions and have informed the Central Bank of the changes made.
Very often consumers think that since the Central Bank registers the financial institutions and their information is published on the website of the Central Bank, it is the National Bank that has the power to resolve disputes between them and financial institutions. For this reason, the C-Bank is receiving complaints from customers of financial institutions. Some of these signals show violations of specific issues related to the Consumer Credit Act, other signals are associated with the interest rates offered by some financial institutions, third object the volume of accrued fees and charges.
As a public institution, Bulgrian National Bank approaches responsibly each complaint and signal and, despite its limited legal powers regarding consumer protection, conducts a detailed examination of the facts and circumstances of each signal or complaint requiring a reasoned opinion from the financial institution and if the case requires it – an on-site inspection at the offices of the financial institution itself. After completing the analysis of the data,
BNB informs the individual applicants
about the conclusions of the examination and the powers of the competent institutions to which the applicant may apply for assistance. For the record , from the beginning of the year so far the Bank has received more than 30 complaints against 14 out of a total of 284 registered financial institutions.
Analysis of complaints showed that in most cases customers were not made closely acquainted with all the important terms of the loan given to them, especially those related to service costs, fees, and penalties for non-compliance due to the agreed repayment terms. Only when they have difficulties with the repayment of their loan do consumers pay attention to the details in the terms of the contracts concluded. There are many cases where relatively expensive loans are not used for the actual urgent and immediate needs and uncalculated expenses are made and, in turn, the costs of such loans prove to be difficult to administer. It is of mutual interest for both parties involved in the process of awarding and receipt of a credit to approach the issue responsibility. Users with difficulties should seek assistance first from their creditor who is in a position to offer assistance in solving the problem.
On the occasion of the many complaints reaching the Bank, the
BNB designed a manual to help users
under the heading Information for customers of financial products and services (address: http://www.bnb.bg/BankSupervision/wwwBSCustomersInformation/index.htm). The guidelines are published on the website of BNB in Banking Supervision , Information for customers. There is a special focus on the procedures and authorities for settlement of disputes between customers and credit or financial institutions. The information is presented in an accessible and understandable way in order to assist users in resolving disputes with both the financial institutions and banks and to guide them to the competent authorities , if necessary.
In short, the Central Bank monitors and may penalize companies for loans in terms of availability of minimum required capital. In connection with the money laundering the control on the companies is vested to the National Security Agency. When it comes to the conditions under which loans are granted to individuals, the heavy word on whether there is a law violation is of the Commission for Consumer Protection. When loans are less than 400 levs, there is no law or institution to protect debtors from their creditors.
The BANKER