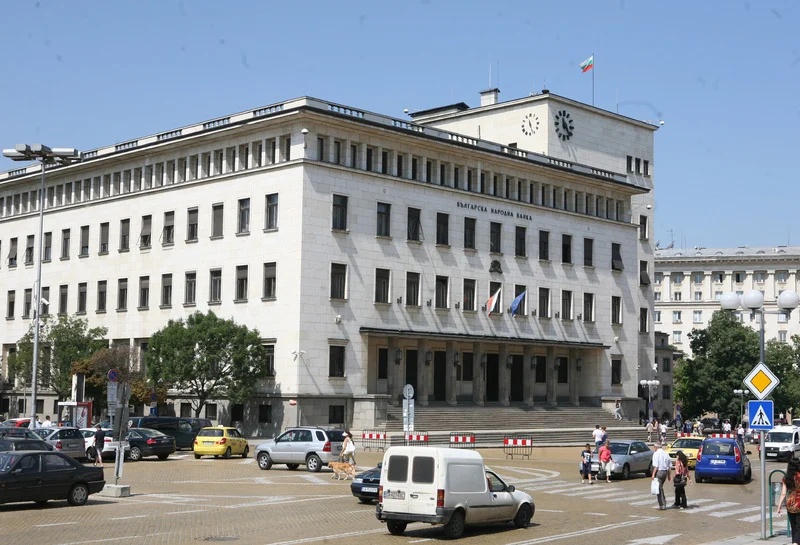
European directives are on their way to put an end to the dispute whether the Bulgarian Central Bank (BNB), as a supervisor, has to take care of the rights of debtors. On Wednesday, the Council of Ministers adopted a draft amendment to the Law on Credit Institutions. The reasoning says that its main purpose is to introduce into the Bulgarian legislation what was adopted in June 2013 by the EU Capital Requirements Directive and the basic regulations for capital requirements prepared on its basis.
The Directive sets out the rules by which National Bank will carry out supervision, the new
disclosure requirements of the banks’ financial status,
the procedures for conducting stress tests according to the results of which their persistence to shocks in the economy will be assessed. The Central Bank is given the power to decide whether to rescue banks. But one of the most important changes is related to the procedures by which the BNB informs and receives information from the European structures for supervising the banking activities – European Banking Authority, the European Systemic Risk Board and the not-yet-created supervision to the European Central Bank. The matter in question is about complicated and purely technical procedures with the aim the supervising department of the BNB and the European Supervisory structures respectively to be quickly and comprehensively informed of problems both in the local and in the European banking sector, while maintaining the level of confidentiality of information.
Certain new rules were introduced
for the provision of information about shareholders
of each bank. Such information will have be to submitted to the Central Bank not only for all persons holding more than 3% of the bank’s capital, but also for the 20 largest shareholders. In other words, if a bank has 19 owners, they will have to submit information to the BNB about their financial situation, regardless of how many shares have.
Mandatory requirements are being introduced for each bank to disclose on their websites their policies in terms of lending, risk assessment, remuneration and also the number of employees. However, most Bulgarian banks do such disclosures at the moment, but they are usually too general and therefore vague. From next year, all banks are required to publish such data.
Furthermore, credit institutions will be required to establish special committees to identify candidates for executive directors of the bank. They will include members of the Supervisory Board and members of boards of directors or boards that do not have representative powers.
To the horror of the bankers and much joy of the citizens after the changes in the law
BNB will be obliged to publish all its penal acts
The matter in hand is about the decisions of the Deputy Governor responsible for managing the Banking Supervision Department or the Board of the Central Bank that impose any kinds of penalties for the violation of the rules of the laws or regulations of the Bank. According to the proposed amendments, the BNB will not only have to announce the supervisory sanction but will publish the breach, the bank that has carried out the specific offense and the names of the officials who are to be blamed for this. However, there is a loophole in the law. The new amendment says that the Bank may limit itself only to disclosing general information, if it considers that the publication of more specific information would threaten the stability of the banking system. Well, this suggests that in most cases of penalties, the Central Bank will most likely decide that the mentioning of more details around the offense (especially if it is a severe one) and the offender may pose a risk of panic on the markets and will not disclose those details.
Another important change in the law is that
it eliminates the protection of clients’ rights
The explanatory memorandum to the draft amendment reads as follows: In order to avoid duplication of legal regimes and legal competencies of various administrative bodies, the repeal of Art. 58 of the Credit Institutions Act. The provisions of this Article do not meet any of the transposed Directives, including the one transposed by this bill, and even less of the Capital Requirements Regulation. The legal framework in the EU consumer protection law is governed by separate directives and national regulations and is assigned to separate national authorities. In fact the law will remove the texts that burden banks with certain commitments to borrowers – what information they are given, what it contains, and so on. This particular Article 58 was intended to be changed by a group of MPs from the socialist BSP and their coalition partners of the ethnic Turk MRF, led by the chairman of the Parliamentary Committee on Budget and Finance Yordan Tsonev, but in the same time strengthening the rights of debtors. Their idea was to prohibit banks from charging fees on loans granted by them, as well as make them form interest rates based on market indices and so on. But most importantly, the amendments will make the C-Bank supervise if banks fulfill these commitments and, in case of severe violations, take their licenses. It turns out, however, that these ideas are not only irrelevant but also contrary to EU directive and regulation on capital requirements.
BNB is to review mostly whether banks in any particular moment can pay their depositors their money if the client so wishes. The solvency guarantees are directly connected with the
capital adequacy requirements
recorded in Regulation 575/2013 of the European Union, known as Basel III. This is the documents that outlines specific capital adequacy ratios, the rules for determining the major and internal credits, the applicable systems and approaches to risk assessment of the various types of financial instruments and all other techniques for calculating and covering the risks that a bank may not be able to collect back certain types of lent resources.
These rules also apply directly to any EU country. They will be introduced by a special decree of the National Bank, which is currently underway. It will replace the current regulations on capital adequacy, for classification and provisioning of troubled receivables, and for large loans. It says that the total capital adequacy ratio that banks are required to maintain will be 8% rather than 12% as it is now.
Additional capital buffers will be introduced, which are mandatory according to EU regulations. These include a conservation and a countercyclical buffer, each of which can reach up to 2.5 % of total risk volume on all claims of a bank. Additionally, there is a buffer for its systematic risk, whose maximum size is 1.5%. The detailed description of each of the buffers, and other new requirements that the EU Regulation will introduce for the Bulgarian banks and the impact that they will have on the Bulgarian businesses are subject to a separate publication. What is important here, is that the new capital requirements will not reduce the current requirements for capital adequacy. According to experts from the Banking Supervision Department, with the application of the Basel III, the C-Bank may introduce capital adequacy requirements up to 13.5% under the current minimum of 12 percent. According to them, the control over the stability of the banking sector will not be loosened.
The BANKER