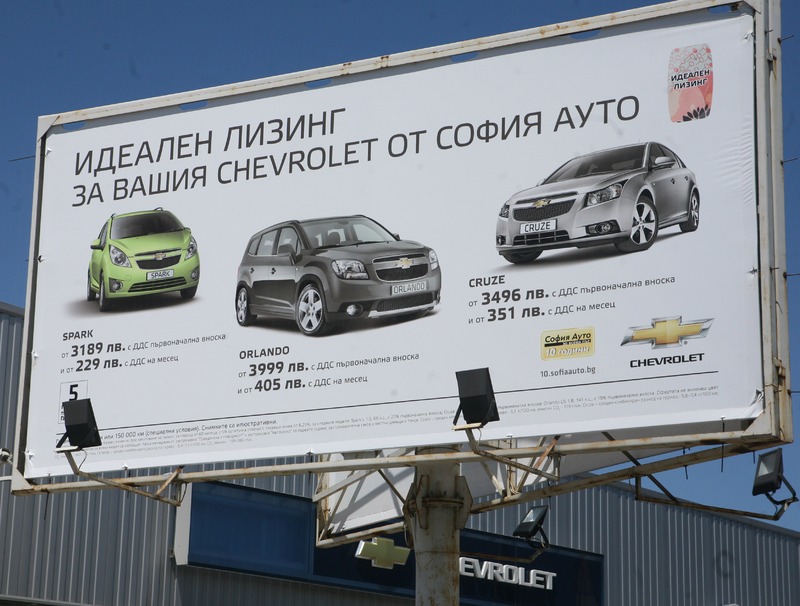
„Since the beginning of the year we have been working with two installment plans – one for the lease payments and the other – for the Value Added Tax,“ Borislav Todorov, co-chair of the Bulgarian Association for Leasing told the BANKER. This in fact means an end to the practice of „open-ended financial leasing“ or a „leasing scheme with an option,“ by which, until recently, it was often possible to avoid VAT. These schemes do not necessarily involve transfer of ownership at the end of the lease and therefore did not trigger the obligation to pay VAT by the new owner – a company or individual. From the first of January this practice has been cancelled.
Mr. Todorov has described the new scheme as follows: „For convenience, let we assume that you want to buy a car for 100,000 levs. We negotiate a 15% advance payment, i.e. 15 000 levs. Onto this payment you are charge VAT of 3000 levs, which shall be paid as soon as the contract is signed. What remains is a sum of 85,000 levs agreed to be paid in installments (the longest period is 60 months, 5 years). The sum bears a VAT of 17,000 levs. This could be paid early at the transfer of the property on the vehicle or through an individual repayment plan. When the term of the contract expires in order for the car to pass into your possession, you must have already paid all the VAT. Therefore still at the signing of the lease contract a repayment plan is to be made for the installments and a second installment plan is signed for the VAT.“
„To explain in details – since 75% of the market, as shown by our recent survey, is for cars and machines, which enjoy the right to a tax credit, the most common practice is our customers who are entitled to a tax credit to seek rescheduling VAT payments for no more than three months. This may seem strange, but this time is enough for them to generate revenue from their new machines or vehicles and pay the VAT due to the state, the amount of which we are have a kind of pre-financed them. If everything is done properly, the country gives them back those 17 000 lev,“ said Todorov.
For passenger cars, which are not entitled to VAT credit, i.e. not above the threshold of 6 +1 seats, usually the clients choose a repayment of VAT obligations on a monthly basis together with the leasing contributions.
The crisis has cut almost a third of the lessors, the survey shows. The number of these companies decreased from 94 at the end of 2011 to 69 at the beginning of this year.
Large and major players in the sector remain the same. Activities have terminated mainly companies that did not have leasing as core business. All non-bank financial companies that lend, lease, provide factoring, etc.., are now required to register with the Central Bank, and receive such registration if they meet certain requirements.
Some of the companies that meet their basic activities offered also leasing (e.g., white and brown household good) or car leasing Car importers no longer exist. These are companies with a smaller area and targets, which have played their role and are no longer in the leasing market, said Borislav Todorov. He confirmed that no serious players have „fallen victim“ of the recession and mone of them have been removed from the register. In fact the current acting companies with typical leasing services are about 20, and with those of the major car importers, their number reaches about 40, he said.
The leasing sector reported a relative stabilization of the business, improvement in the collection of overdue leasing installments and reduction of non-performing obligations. In 2013, the majority of our customers were able to restore the regularity of payments under the contracts, the transport sector has started to recover as early as 2011, and we are financing also the purchase of equipment under the programmes of EU, said Todorov. However, according to him the sector of leasing companies will begin to report gains when economic growth in the country becomes more evident. Expectations for 2014 are that it will not be much different from last year. And experts make it clear that a prerequisite is the availability of economic growth that would create incentives to allow businesses to invest.
People often ask – which means, for example, to opt to acquire a car: loan or lease. Usually, the annual interest rate on lease and bank loans is between 5% and 8%, but one should remember that there are management fees, so the effective annual costs are higher. The interest rate depends on the initial payment and the term of the lease or loan. If the installment is higher and the term of payment – shorter, then the interest rate is lower.
In the most common case, the payment of the car for five years accumulate about 20% over the automobile’s value at which the monthly installments are paid.
The main difference is that when you use credit, the client still at the beginning becomes the owner of the car. But this does not mean that is one’s name appears on the coupon, the holder can immediately sell it. The car serves as collateral and is entered in the register of pledges.
In the granting of the credit for the purchase of a car banks have a requirement for higher self participation in the payment of the first installment 20-30% of the value of the car, while the leasing companies can as for as low as 5 to 10%.